Getting recognized
When a possible heir writes to the servicer, the servicer has to respond with a description of the documents it needs to confirm that person. Once confirmed, an heir is treated as a borrower under the federal servicing rules.
When a homeowner dies, the mortgage stays with the property, and the servicer often refuses to speak with the family. Federal rules give heirs a path to be recognized, and federal law limits a lender's power to call the loan due because of the transfer. Before you decide to keep, sell or refinance, you need to know what is owed and whether the record holds up.
These records decide what you owe and who can collect it. They are rarely sent to you, and almost never explained. We request them, examine them and tell you in plain language what they prove and what they do not.
When a possible heir writes to the servicer, the servicer has to respond with a description of the documents it needs to confirm that person. Once confirmed, an heir is treated as a borrower under the federal servicing rules.
For homes with fewer than five units, a lender generally may not demand full payment because the property passed to a relative when the borrower died, or because it was placed in a living trust the borrower still benefits from.
We reconcile the servicer's payment history, escrow account and fees, so the estate works from a verified figure.
We document who owns the loan and whether the transfers behind it were recorded.
We check for unreleased liens and gaps that would hold up a transfer, a sale or a refinance.
We do not promise results, and every file depends on what its records show. When a dispute is documented and pursued properly, these are outcomes it can produce:
The payoff figure decides what is left for the estate after a sale. The video explains who calculates it and how to get the math in writing, and the sample report shows what a finished examination looks like.
A foreclosure sale is run by a substitute trustee who is expected to be neutral. This short video follows the money from the high bid to the surplus, names the three documents that decide the number, and gives four ways to get the math in writing.
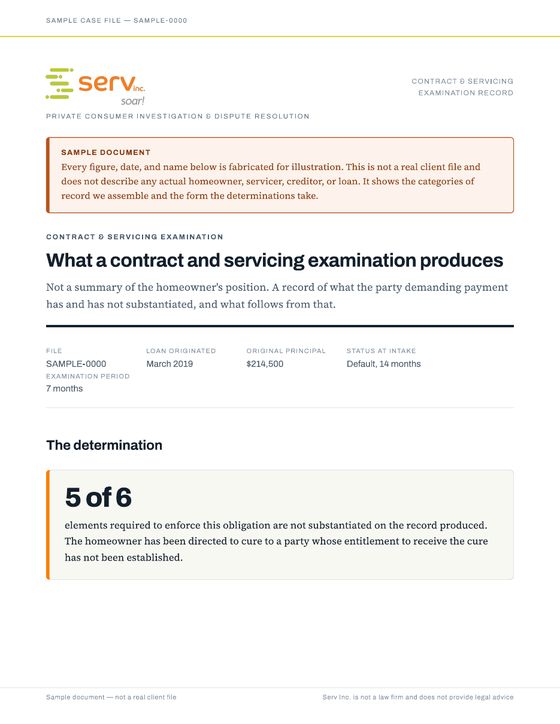
A complete sample examination record, with every figure made up for illustration. It shows the determination on each element the other side has to establish, the charge-by-charge audit, the response deadlines, and what a homeowner can do with the result.
Open the sample reportIn most cases, no. For homes with fewer than five units, federal law generally bars a lender from demanding full payment just because the home passed to a relative at the borrower's death. The loan continues on its terms, and payments still have to be made to avoid default.
Write to the servicer at its address for information requests, say that you are a possible heir, and ask what documents it needs. The servicer has to answer in writing with that list. We prepare the request and track the response.
An estate plan is built on what you own and what is owed against it. We give you and your estate planner the facts from the record: the balance, who can enforce the loan, and whether the title is clear. Your attorney or planner decides which protections fit.
We do not promise outcomes. We can move quickly to get you recognized by the servicer, examine the file for errors under the federal servicing rules, and put what we find in writing while there is time to use it.
Upload your documents and we will send a free summary of what the record establishes, what is missing and why it matters.